Don’t Get a Letter from Your Doctor if You Have to Cancel Your Trip

I don’t know where people get the idea that they need a letter from their doctor if they get sick or injured and have to cancel their trip.

But I see it all the time.

People get sick or injured, visit their doctor, and ask for a letter saying they shouldn’t travel. They assume that’s what the travel insurance company needs to pay their Trip Cancellation claim.

Unfortunately, that letter can create more problems than it solves.

Deanna, Kim and I have seen doctors’ letters that contain incomplete information, contradict the travel insurance policy’s requirements, or describe medical conditions that might not even qualify for coverage.

And the worst part? The traveler often has no idea there’s a problem.

What Does Your Travel Insurance Policy Actually Require?

If you have to cancel your trip because of your own Sickness or Injury, this is what our policies typically state, with minor wording variations that convey the same information:

Your Sickness or Injury, that:
a. occurs before departure on Your Trip;
b. requires the in-person Medical treatment by a Physician prior to cancellation; and
c. as certified by a Physician prior to cancellation, results in medical restrictions so disabling as to cause You to cancel Your Trip.

Read that carefully.

Nowhere does it say you must get a separate letter from your doctor.

What it does say is that you must receive the required medical treatment before canceling your trip and that your physician must certify, before cancellation, that your medical restrictions are so disabling that you have to cancel.

Those are important requirements.

Your insurance company will also require documentation supporting your claim. This commonly includes an Attending Physician’s Statement or another medical certification form that your doctor completes as part of the claims process.

That’s different from asking your doctor to write an unsolicited letter saying you shouldn’t travel.

Why I Tell People Not to Get a Doctor’s Letter

When customers call me and read their doctor’s letter, I often tell them:

“Tear up that letter and throw it away. Don’t send it to the insurance company.”

Why?

Because many of these letters don’t establish what the insurance company actually needs to know.

Sometimes they’re vague. Sometimes they’re incomplete. And sometimes they contain statements that could undermine an otherwise legitimate claim.

Unfortunately, not everyone takes my advice.

Here are three examples of actual doctors’ letters customers have shared with us when they were considering canceling their trips.

Doctor’s Letter #1: A Medical Condition Doesn’t Automatically Justify Canceling Your Trip

Please excuse my patient ____ from flying and traveling via ship because of her lumbar spine stenosis. She suffers from intermittent back pain radiating to the leg.

What’s wrong with this letter?

First, the doctor identifies a medical condition, but that doesn’t necessarily establish a covered reason for Trip Cancellation.

Second, the letter doesn’t explain whether the patient received the required medical treatment before canceling.

Third, it doesn’t explain what medical restrictions were so disabling that the patient couldn’t take the trip.

The doctor simply says the patient should be excused from traveling.

Having a medical condition isn’t the same as having a covered medical reason to cancel your trip.

For example, someone might have lived with back pain for years and still be able to travel. If the condition suddenly becomes significantly worse, that’s a different situation that needs to be evaluated under the policy’s terms.

The insurance company needs to understand what happened medically, when it happened, and why the condition required cancellation

A short letter like this doesn’t establish those facts.

Doctor’s Letter #2: A Difficult Trip Isn’t Necessarily a Medical Emergency

______ is a patient of mine. He has a trip to Europe scheduled for September 16 – 30, 2026. The trip will be harder than he expected, so I don’t think it’s a good idea he take the trip.

This is another example of a letter that could cause problems.

The doctor doesn’t identify an illness or injury.

There’s no mention of medical treatment.

There’s no explanation of disabling medical restrictions

Instead, the doctor says the trip will be harder than expected and doesn’t think the patient should go.

Travel insurance generally doesn’t cover canceling a trip simply because the trip might be too difficult.

That’s not the same as having a sickness or injury that satisfies the policy’s requirements for Trip Cancellation.

There may be additional medical circumstances that could support this customer’s claim, but the letter doesn’t explain them.

And that’s precisely the problem.

Doctor’s Letter #3: “Could Potentially Prevent Travel” Isn’t the Same as Being Unable to Travel

_____ is under my medical care for treatment of a serious illness. During our office visit on August 10th, 2026, patient was diagnosed and informed of the need for monthly treatments which could potentially prevent him from traveling over the next several months.

This letter is especially interesting.

Unlike the first two examples, it identifies a serious illness, refers to an actual office visit, and describes ongoing medical treatment.

That’s useful information.

But look at the last part:

“Could potentially prevent him from traveling.”

Those four words create uncertainty.

The doctor isn’t saying the patient was medically unable to travel. The doctor is saying the treatments might prevent travel.

There’s a big difference.

Under the policy language quoted earlier, the physician must certify before cancellation that the medical restrictions are so disabling that the traveler has to cancel the trip.

The possibility that treatment might interfere with travel doesn’t necessarily satisfy that requirement.

A properly completed medical certification would need to establish whether the patient actually had disabling medical restrictions requiring cancellation, rather than merely anticipating a possible scheduling conflict.

What Should You Do Instead of Getting a Doctor’s Letter?

If you become sick or injured and think you might have to cancel your trip, here’s what I recommend.

1. Get the medical treatment you need before canceling your trip.

Don’t wait until after you’ve canceled to see your doctor.

If your policy requires in-person medical treatment before cancellation, a telephone conversation or an email to your doctor might not satisfy that requirement.

2. Make sure your doctor understands your travel plans.

Tell your doctor when you’re scheduled to leave, where you’re going, and what your trip involves.

More importantly, make sure your doctor evaluates whether your illness or injury creates medical restrictions that actually prevent you from taking the trip.

3. Make sure your medical restrictions are documented before cancellation.

If your physician determines that your condition requires you to cancel, that determination needs to satisfy the requirements of your particular policy.

Don’t assume that simply being diagnosed with an illness automatically qualifies you for Trip Cancellation benefits.

4. Contact us before canceling your trip.

If you bought your travel insurance through TripInsuranceStore.com, call us before canceling whenever possible.

We can help you understand the applicable policy language and the claims process so you don’t make an avoidable mistake.

We can’t guarantee that your claim will be paid, but we can help you understand what the insurance company requires.

If you have a medical emergency, get the necessary care first. And don’t delay notifying your travel suppliers once cancellation becomes necessary, because your policy requires prompt cancellation to limit your financial loss.

5. Have your doctor complete the insurance company’s required medical forms.

When you file your claim, the insurance company will require an Attending Physician’s Statement, a Medical Certificate, medical records, or other supporting documentation.

These documents are designed to establish the medical facts relevant to your claim.

Have your doctor complete the required forms accurately and thoroughly.

And remember: Your doctor should document the actual medical findings and restrictions, not simply write whatever might help get your claim paid.

The Bottom Line: Get Medical Treatment, Not an Unnecessary Letter

If you have to cancel your trip because you’re sick or injured, don’t automatically ask your doctor to write a letter saying you shouldn’t travel.

A doctor’s letter doesn’t make your Trip Cancellation claim valid. The medical facts and your policy’s coverage requirements determine whether your cancellation is covered.

Get the required medical treatment before canceling. Make sure your physician documents the medical restrictions that require cancellation. And submit the medical documentation your insurance company actually requests.

A vague or poorly worded doctor’s letter isn’t a substitute for satisfying your policy’s requirements.

If you bought your travel insurance through TripInsuranceStore.com and think you might have to cancel your trip, call us before you cancel.

We’d rather help you avoid a claims problem than try to fix one after it happens.

Important: Travel insurance policies differ. The specific terms, conditions, exclusions, medical certification requirements, and claims procedures in your policy determine your coverage.

Finally, if you potentially would want to cancel your trip because you might not feel good, some of our plans offer the 75% Trip Cancellation for Any Reason as an optional upgrade.


{ Comments on this entry are closed }

I hope this makes sense. If you want the right travel insurance advice, call us at 1-888-407-3854 and we'll help you figure it all out.

Now, a word from our sponsor: TripInsuranceStore.com (Travel Forums' Most Recommended Travel Insurance Website)

PS - If you liked what you read, please Subscribe to my Blog.

No Doctor, No Claim: The Rule Too Many Travelers Forget

by Steve Dasseos on April 29, 2026

No Doctor, No Claim: The Rule Too Many Travelers Forget

If you’ve ever purchased a travel insurance policy from us, you’ve received our “Consumer’s Guide to Having a Successful Travel Insurance Claim With These 9 Travel Insurance Claim Tips”.

And, at the very top is the most important rule:
Tip #1: If you get sick or injured prior to or on your trip, it is important you go to a doctor. If you do not go to a doctor, the insurance company will not believe you were sick or injured.

If you don’t, your claim is very likely to be denied.

Most policies say something like:

“For Trip Cancellation benefits, an actual examination by a licensed Physician must take place before the cancellation is made. For Trip Interruption benefits, this examination must take place during Your Trip.”

This isn’t a technicality—it’s the foundation of whether your claim gets paid.


Real Calls I’ve Received

Case #1: “We came home early… but didn’t see a doctor there”

A client called after returning early from Ireland

“My husband hurt his back badly, so we came home early. We saw a doctor once we got back, and he said it was a good decision. What do we need to do for the claim?”

I asked one key question:

“Did he see a doctor while you were still in Ireland?”

The answer was no.

They chose to finish their planned activities first, then fly home early, and only saw a doctor after returning.

I explained:

You absolutely have the right to file a claim, but without a doctor visit during the trip, it’s very unlikely the claim will be paid.


Case #2: “I could’ve gone…”

Another long-time client told me:

“I got sick in Spain before our cruise. I stayed in the hotel, took care of myself, and we flew to meet the ship a few days later. I could’ve gone to the doctor, but I figured a doctor would just tell me to do what I was already doing.”

He was right about one thing—he did know he could’ve gone.

But because he didn’t see a doctor in Spain, his $3,300 claim was at serious risk.

His response:

“I need you to convince the insurance company to pay this.”

Unfortunately, this isn’t something anyone can “convince” a company to overlook.
The requirement is written into the policy.


Case #3: The One I Never Forget

This one goes back to 2009.

A woman called about a Trip Interruption claim after falling on ice in Iceland and breaking her wrist.

I asked if she saw a doctor.

She said:

Yes. Do you think I’m stupid? Of course I saw a doctor!

Then we talked further.

She actually didn’t see a doctor in Iceland.

She waited until she got home to Arizona—five days later.

She told me she nearly passed out from the pain while traveling home.

And unfortunately, that meant her claim was in jeopardy.


Why This Rule Exists

Insurance companies aren’t trying to make things difficult.

They need:

  • Verification that something actually happened
  • Documentation of when it happened
  • Medical opinion supporting your decision to cancel or interrupt

Without that, there’s no way to validate the claim.


The Simple Rule to Remember

If something happens on your trip:

👉 See a doctor before you cancel, interrupt, or change your plans.
👉 Follow their advice.
👉 Keep the documentation.

Even if it feels unnecessary… do it anyway.


The Good News

These situations are actually rare.

Most travelers:

  • See a doctor when needed
  • Follow instructions
  • Keep records

And their claims are paid without issue.


Final Thought

Travel insurance works—but only if you follow the rules.

And the most important one is simple:

No doctor = no claim.


If you ever have a situation during your trip, call us first.
A 2-minute conversation can be the difference between a paid claim and a denied one.


{ Comments on this entry are closed }

I hope this makes sense. If you want the right travel insurance advice, call us at 1-888-407-3854 and we'll help you figure it all out.

Now, a word from our sponsor: TripInsuranceStore.com (Travel Forums' Most Recommended Travel Insurance Website)

PS - If you liked what you read, please Subscribe to my Blog.

Why Are my Non-Traveling Family Members Important?

by Steve Dasseos on October 26, 2025

“We don’t have any non-traveling family members. It’s just the two of us taking the trip. Everyone else is staying home and aren’t going on the trip with us. Why does it matter?”

I received this email response as an answer to “In the last 180 days, have any non-traveling family members had any medication changes or had treatment for, had symptoms of or been diagnosed with any medical condition that could worsen and, in turn, cause you to cancel or interrupt your trip?

I wasn’t sure how to respond to that without making them look stupid, so I only answered their question.

Why do my Non-Traveling Family Members matter?

Our trip insurance plans cover you for canceling or interrupting if you or they get ill or injured (i.e. – get hit by a cement truck).

In addition, it’s important to know about your Non-Traveling Family Members’ health because they might have some serious medical condition today that could worsen and cause you to cancel or interrupt your trip.

However, it’s possible (more likely in large families) that one of those Non-Traveling Family Members has a medical condition.

I’m 68 and my parents are 92 and 94. It’s a blessing that they are still around, but my Dad has pre-leukemia MDS (myelodysplastic syndrome). Because of this, when I buy Trip Cancellation insurance, I always get a plan that covers Pre-Existing Medical Conditions should my Dad’s health take a turn for the worse.

How is a Family Member Defined?

A Family Member usually means your spouse or domestic partner, child, spouse’s child, daughter-in-law, son-in-law, brother, sister, mother, father, grandparents, grandchild, step-brother, step-sister, step-parents, parents-in-law, brother-in-law, sister-in-law, aunt, uncle, niece, nephew, guardian, ward.

Now that you know about this, you also need to know that the vast majority of Trip Cancellation insurance plans require you to buy the plan within a short amount of time after your earliest payment of any kind toward any travel arrangements on your trip to have the “Waiver of the Pre-Existing Medical Condition Exclusion“.

That date is called the “Initial Trip Deposit Date” and any payment including taxes on frequent flier tickets or giving a credit card to guarantee a reservation counts as this date.

If your Initial Trip Deposit Date was more than 21 days ago, we have a few plans that always cover stable medical conditions of your non-traveling family member.
…


{ Comments on this entry are closed }

I hope this makes sense. If you want the right travel insurance advice, call us at 1-888-407-3854 and we'll help you figure it all out.

Now, a word from our sponsor: TripInsuranceStore.com (Travel Forums' Most Recommended Travel Insurance Website)

PS - If you liked what you read, please Subscribe to my Blog.

Am I Able to Travel?

by Steve Dasseos on June 17, 2025

When a Trip Cancellation plan’s wording includes “You are medically able and not disabled from travel at the time Your premium is paid based on assessment of a Physician”, do I literally have to get a note from my doctor right now that says I am medically able and not disabled from travel before I buy the policy?

These are good and very timely questions. All Travel Insurance plans require you to be able to travel on the date you buy it.

Erroneously, most people think that the ability to travel only matters if you want the pre-existing medical condition coverage. However, the truth is that in order to be eligible to buy any travel insurance plan, you have to be able to travel on the date you buy it.

Nearly everyone is able to travel, but there are situations where that’s not the case. If any of these are true today, you aren’t able to travel:

  • You are in the hospital now.
  • If you recently got out of the hospital, you likely aren’t able to travel.
  • You have specifically been told by your doctor you can’t travel.

So, how do you document if you are able to travel? If you’re not sure, ask your doctor. If you have a Patient Portal, it’s best to send them a message so you have a document trail.

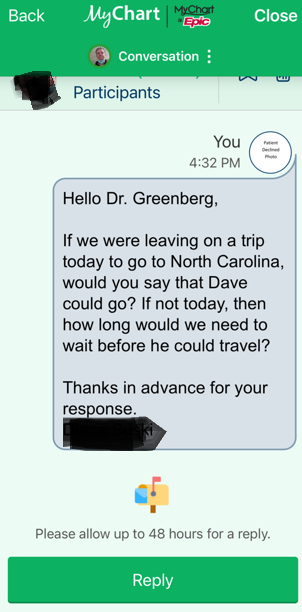
Here are screenshots from someone asking their doctor if Dave can travel today. The message was sent through the Patient Portal, so RN Jessie is who responded.

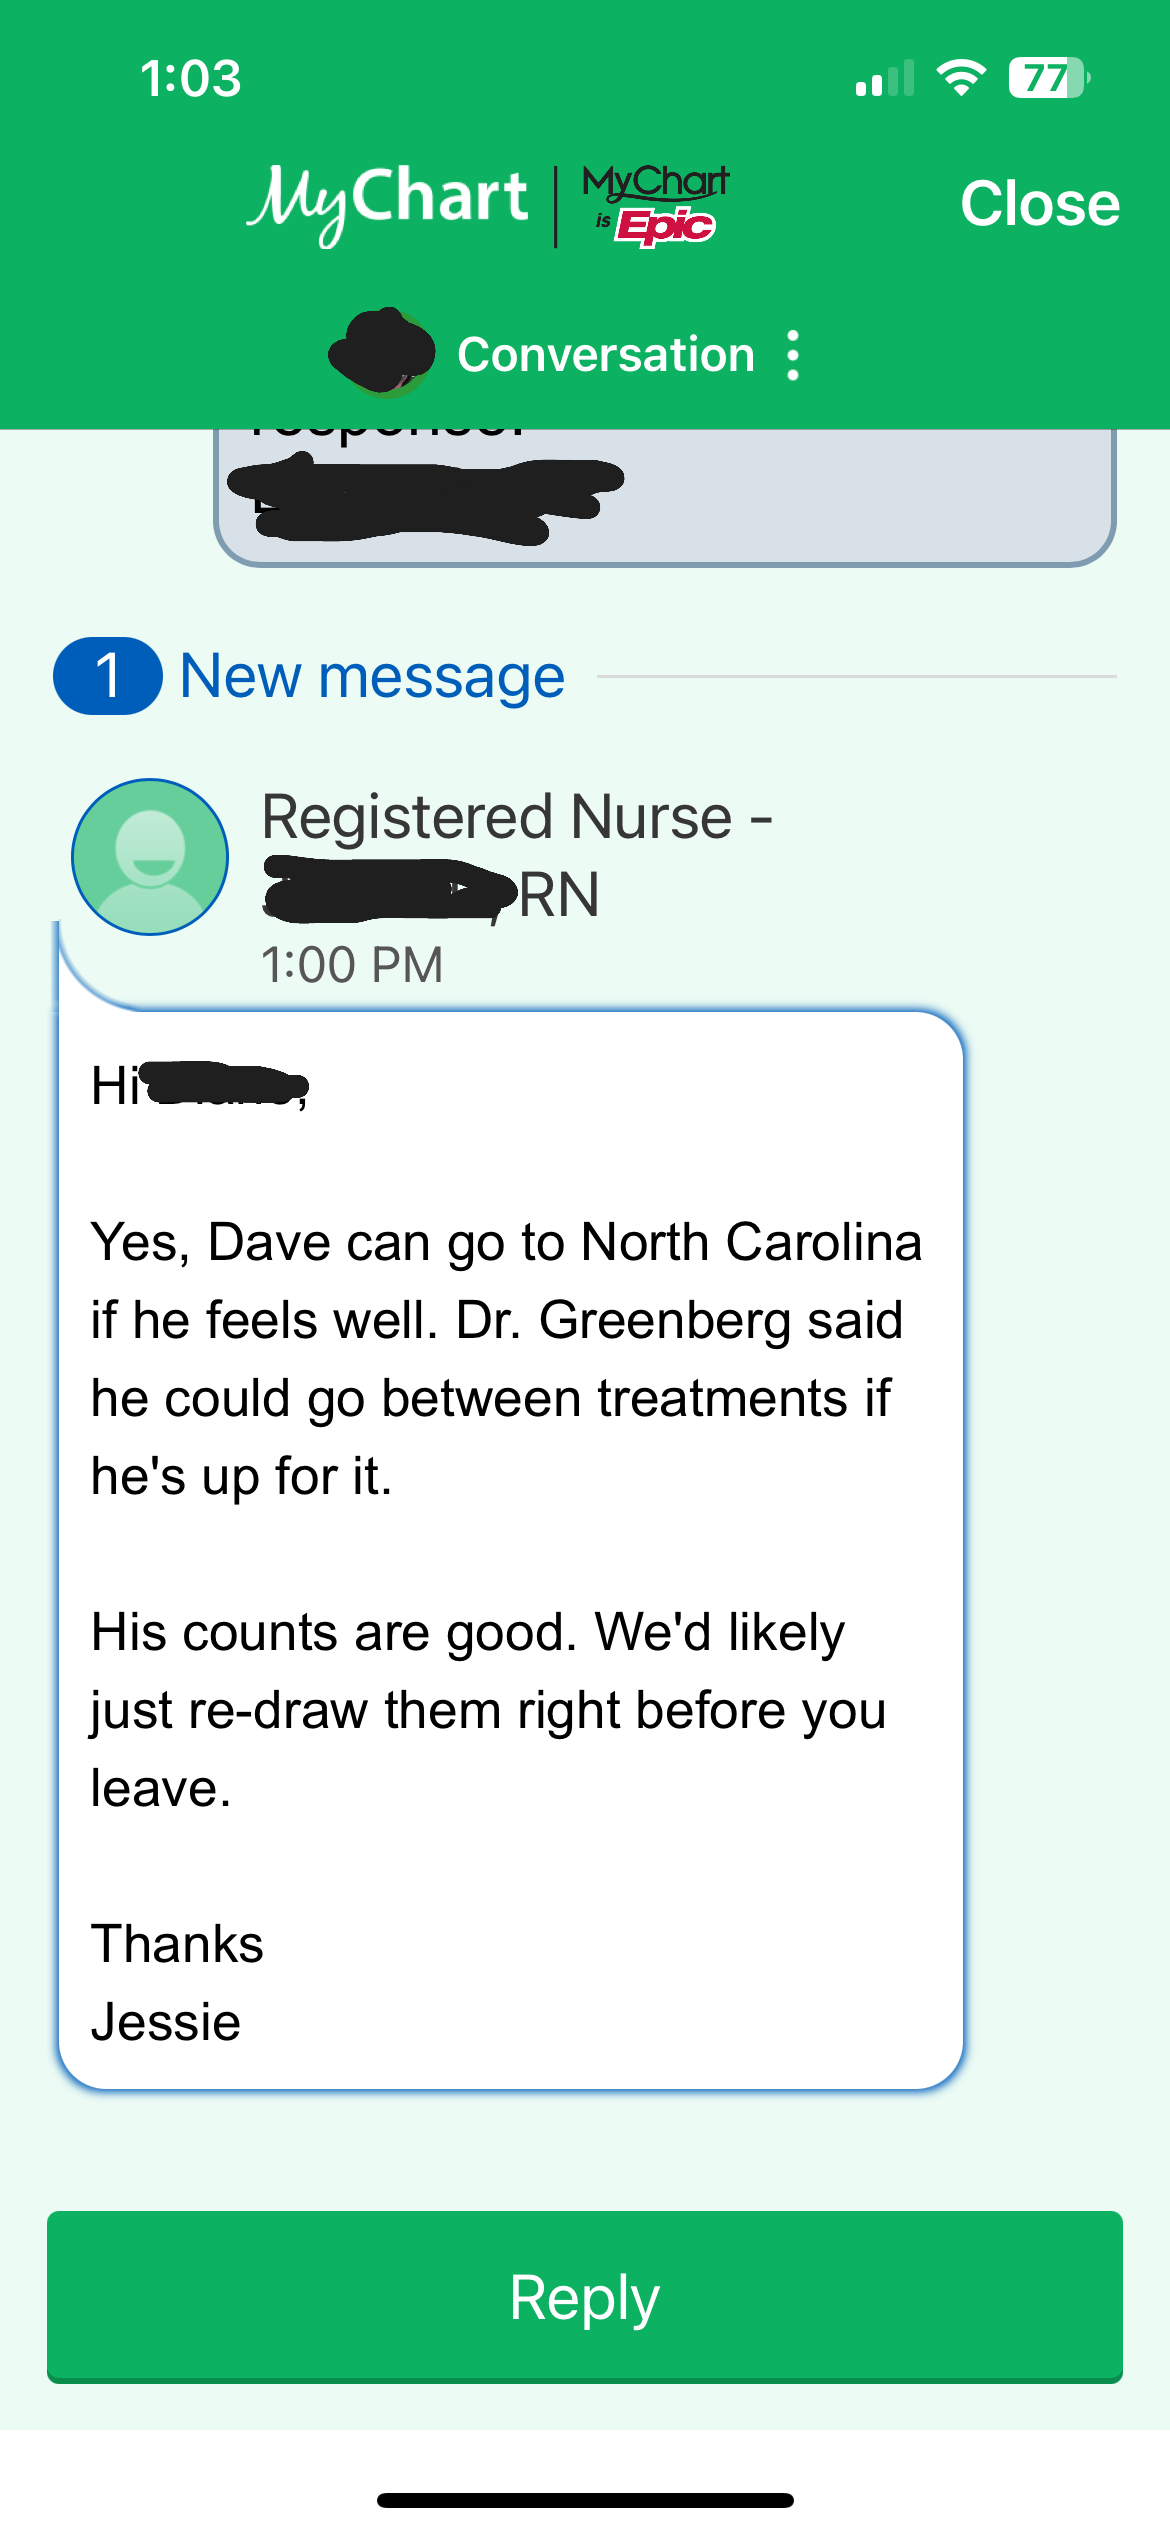
And, here’s Doctor Greenberg’s response via Jessie:

If Dave were to have any claim, they now have documentation he was able to travel.

Another reason to ask is if your doctor dies. I’ve seen this happen where someone’s being treated for a medical condition and after they received documentation that they were able to travel, before their trip, their doctor passed away. One of these people ended up with a large claim that was only paid because they had the documentation. Their new doctor wouldn’t certify his ability to travel because it was before knew each other.


{ Comments on this entry are closed }

I hope this makes sense. If you want the right travel insurance advice, call us at 1-888-407-3854 and we'll help you figure it all out.

Now, a word from our sponsor: TripInsuranceStore.com (Travel Forums' Most Recommended Travel Insurance Website)

PS - If you liked what you read, please Subscribe to my Blog.

The Credit Card You Should Take on Your Trip

by Steve Dasseos on February 6, 2025

Which Credit Card should you take for trips outside the USA?

This is a nice set up for me to promote specific Credit Cards (and earn commissions), but I won’t do that. Instead I’ll give you practical and actionable advice that helps you today.

Do Not take the Credit Card you use every day

You likely use one Credit Card for most of your transactions. While it’s a good idea to track of all your spending in one place, it’s a bad idea to take that same Credit Card with you when you travel outside the USA.

And, if your primary card’s compromised and cancelled, you’ll be left without access to funds and will potentially disrupt your ongoing payments and subscriptions.

Instead, take two Credit Cards that are issued by a bank that you do not have any other ties to and only use them when you travel outside the USA. Use one for your transactions and have the other as a backup.

Why? Identity Theft, including Medical Identity Theft, is real. You don’t want to unwittingly help online scammers build a detailed online profile about you as a potential victim.

If your main Credit Card’s stolen, the criminals can access your Transactional History which gives them valuable financial insights that help them steal money, commit fraud or tailor specific scams just for you to deceive you more effectively.

Why Would Scammers Want Your Transactional History?

  • To Identify Your Spending Patterns: They’ll see where you spend money, learn about your day to day life and what’s important to you.
  • To Steal Your Credit Card Details: If they get access to your credit card statements, they can attempt unauthorized transactions or sell the information.
  • Commit Identity Theft: Transactional history contains personal details that can be used to impersonate you or open new accounts in your name.
  • To Bypass Security Checks: Banks sometimes ask for recent transactions as a security question. If a scammer knows your history, they can pass verification steps.
  • To Create Targeted Phishing Scams: They might send you fake emails or messages that match your real transactions, tricking you into clicking malicious links.

And, there are two more important things to do:

  • Call the Credit Card company’s International Security department before you leave and be sure to make a call log of who you speak with. Get the International 24/7 Security reporting contact phone number that’s answered by a live human being along with their website. Tell them which countries you’ll be visiting and the dates you’ll be outside the USA. Also, give them your contact information.
  • You need to have the RFID shielded sleeves for your credit cards, passports and hotel room key card. Here’s an Amazon link that I don’t benefit from:
    https://www.amazon.com/s?k=RFID+shielded+sleeves

I know this was a lot of information, but I hope everyone reading this takes it to heart and follows through on my advice.


{ Comments on this entry are closed }

I hope this makes sense. If you want the right travel insurance advice, call us at 1-888-407-3854 and we'll help you figure it all out.

Now, a word from our sponsor: TripInsuranceStore.com (Travel Forums' Most Recommended Travel Insurance Website)

PS - If you liked what you read, please Subscribe to my Blog.

Insuring Travelers in Different States

December 31, 2024

Subscribe Hi Steve, My girlfriend lives in New Mexico. I live in Washington. We’re planning a two-week self-directed trip to Spain. We haven’t paid any deposits, but expect to do so soon. I’m told we have to have two insurance policies. That would double the premium. Our total trip costs are about $18,000. I’m 68, […]

Read the full article →

What Does “Proof of Payment” Mean on My Claim Form?

November 11, 2024

Subscribe What Does “Proof of Payment” Mean on My Claim Form? Hi Steve, Thanks for the help you are giving with Max’s claim, very much appreciated. It’s been very difficult to say the least. Their strategy seems to be to make it as difficult as possible to avoid paying a claim. We put together very […]

Read the full article →

You’ll Save a Lot of Money with Non-Refundable Hotels

September 8, 2024

Subscribe Hi Steve, I’m glad I called you. I wasn’t expecting any advice beyond learning how Trip Cancellation Travel Insurance could help me. Your tip saved me more than $1,310 which almost paid for the insurance I got from you and it will continue to save me money in the future. Thanks for mentioning this […]

Read the full article →

Do This for a Better Baggage Claim Outcome

August 25, 2024

Subscribe Everyone who buys travel insurance from us gets a copy of “The Consumer’s Guide to Having a Successful Travel Insurance Claim With These 9 Travel Insurance Claim Tips” about a month before you leave. Tip #9 is about Baggage coverage. Have you ever had your baggage lost or stolen? If so, it’s nearly impossible […]

Read the full article →

Get Your Trip Cancellation Claim Paid in Full

July 1, 2024

Subscribe Hi Steve, My husband and I booked a Celebrity cruise for about $8,000. How much is a good Trip Cancellation plan? This sounds like a simple request, right? It isn’t, but not for obvious reasons. In fact, because of the apparent simplicity, had they not called us, they probably would have lost $2,405 on […]

Read the full article →

Your Social Security Retirement Benefits are Complicated

June 3, 2024

Subscribe I am grateful and fortunate to have a wonderful community of kind-hearted customers, each of whom excels in their respective fields. What they have in common is their selfless desire to help others. As you’re aware, I seldom endorse businesses, and the few I do, do not compensate me in any way. The only […]

Read the full article →